Hong Kong RBC in 2026: the actuarial, capital and data team you need
- Recruitment
- 8 min read
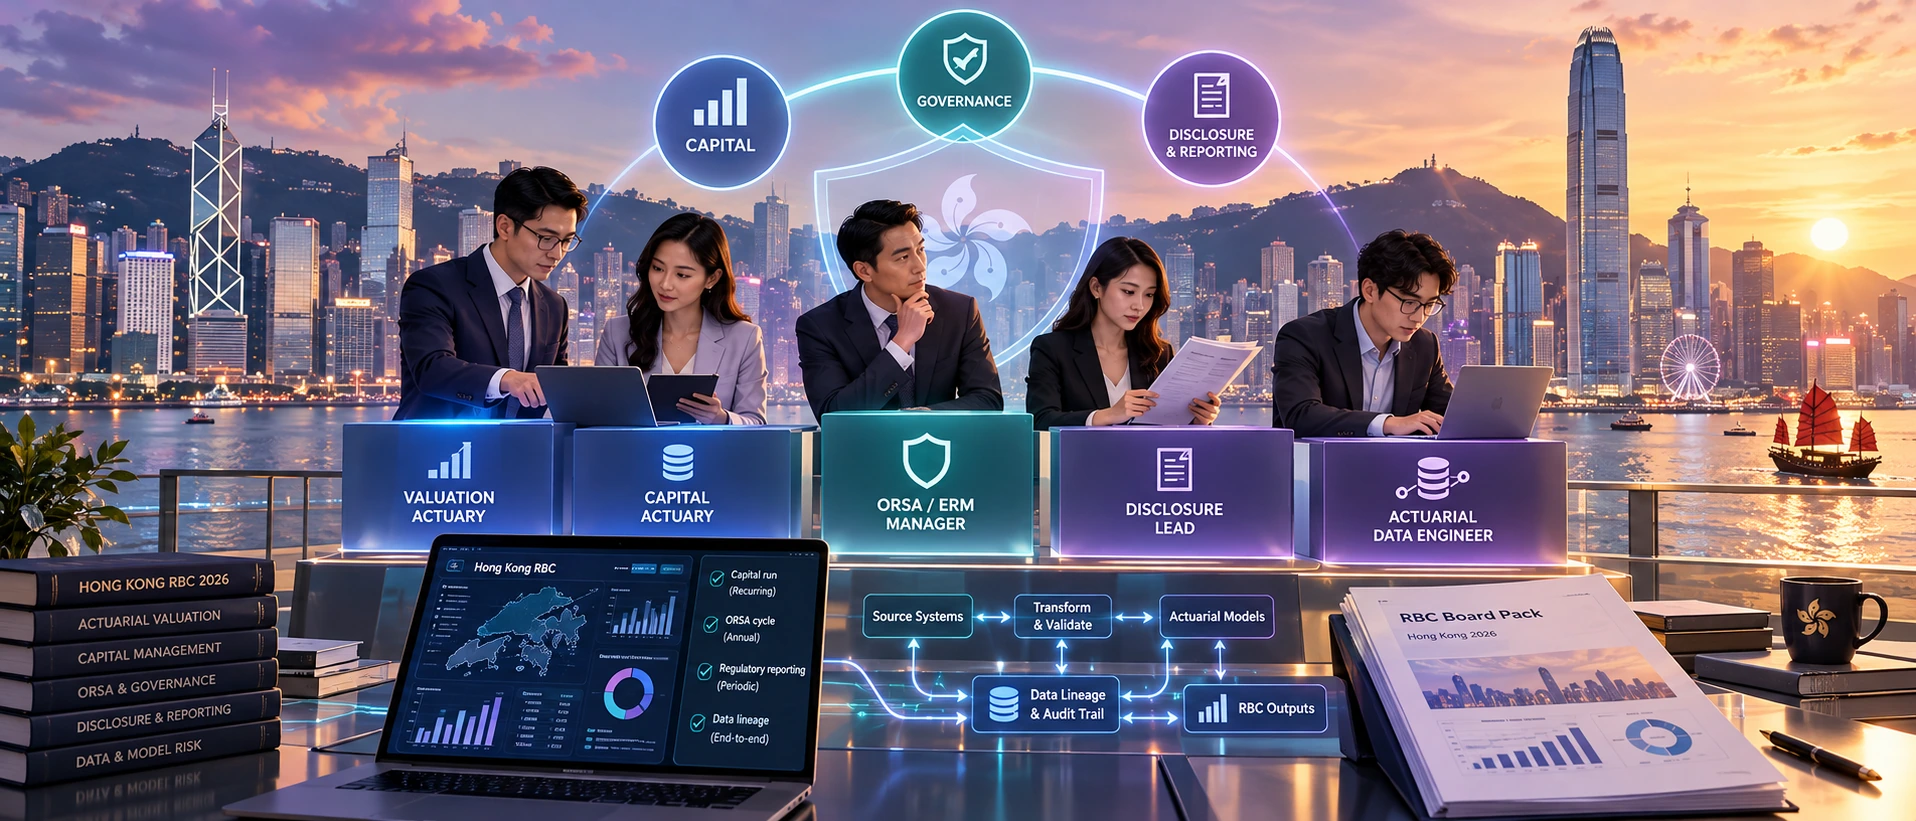
Hong Kong’s risk based capital regime has been live since 1 July 2024, and 2026 added public disclosure rules and capital amendments effective 31 December 2026. Insurers now need an operating team rather than a project team: valuation and capital actuaries, an ORSA owner, a disclosure lead and data engineers who can reproduce every number.
What changed in 2026 now that RBC is live?
Two sets of rules, both gazetted by the Hong Kong government on 22 May 2026. The first, the Insurance (Public Disclosure) Rules, came into force on gazettal and apply to financial years beginning on or after 1 January 2025. For an insurer with a calendar financial year, the 2025 year is already in scope, so the disclosure work is live now rather than next year.
The second, the Insurance (Valuation and Capital) (Amendment) Rules 2026, take effect on 31 December 2026. Among other changes they refine the capital treatment of catastrophe and reserve risk. That lands on the first year end after the amendment, which means someone has to rerun the numbers, explain the movement and get it through governance before the close.
For context, the regime itself commenced on 1 July 2024, following the government’s announcement on 3 May 2024 that 14 pieces of subsidiary legislation had been gazetted. The implementation project is over. The operating burden is not.
Which roles does the regime keep busy after go live?
Every pillar creates recurring work. The framework the Insurance Authority built rests on three: quantitative capital requirements, with the prescribed capital amount calibrated to a 99.5 per cent level over one year; governance and enterprise risk management, including an own risk and solvency assessment (ORSA) at least once a year; and reporting and public disclosure.
Role | Pillar | What keeps them busy after go live |
Valuation actuary | Capital | Quarterly and annual runs, assumption changes, reconciliation to IFRS numbers |
Capital actuary | Capital | Prescribed capital amount, sensitivities, the 2026 catastrophe and reserve risk changes |
ERM or ORSA manager | Governance | The annual ORSA, risk appetite, stress testing with the business |
Model validation lead | Governance | Independent review of capital and valuation models |
Disclosure and regulatory reporting lead | Disclosure | Public disclosures under the 2026 rules, templates, audit trail |
Actuarial data engineer | All three | Lineage from policy systems to capital output, rerun on demand |
The data engineer is the role most often missing. When the regulator or the auditor asks why the capital ratio moved, the answer has to be reproducible from source, not rebuilt in a spreadsheet the night before. When we scope a capital team through our actuarial recruitment practice or risk and financial advisory recruitment, we usually argue for one.
Does every hire need Hong Kong RBC experience?
No, and insisting on it is the fastest way to stall a search. The regime has only been live since July 2024. Anyone with several years of Hong Kong RBC operating experience is, by definition, rare, and most of them are already in a job they just built.
Experience from other risk based capital regimes transfers well. A capital actuary who has run a 99.5 per cent one year calibration in a European or another Asian regime understands the mechanics. What they need to learn is local: the Insurance Authority’s expectations, the Hong Kong disclosure templates, and how the local product mix behaves under the rules. That is weeks of learning, not years.
The Hong Kong government seems to agree. Its Talent List includes actuaries and cites the RBC regime and new accounting standards as demand drivers, which suggests part of this capability is expected to come from outside Hong Kong. The regional picture is in why actuaries are in high demand across Asia Pacific.
Where local experience genuinely matters is the disclosure lead and anyone facing the regulator directly. Even there, a candidate who has owned public disclosure under another regime is often a better bet than a local candidate who only fed numbers into it.
Is Cantonese needed for actuarial and risk roles?
For most capital, valuation and validation roles, no. The models, the reports and most internal governance run in English, and the skill that decides performance is technical. Cantonese matters where the role faces local distribution, claims or customers, and Putonghua can matter where the parent group is on the mainland.
The problem is hidden requirements. A recurring complaint among English speaking professionals in Hong Kong job forums is finding out at final interview that the team expected Cantonese all along. If the role needs it, put it in the brief. If it does not, say so, and you widen the pool considerably.
What should the board see?
A capital position the directors can challenge, not a stack of templates. The ORSA has to be a document the board owns, which means someone on the risk or actuarial side must write for directors: the capital ratio against the prescribed capital amount, what drives it, and how it would move under a catastrophe or a reserve shock.
This is a hiring point as much as a reporting one. The chief actuary or chief risk officer who explains capital clearly to a non technical board is worth more than one who produces perfect numbers nobody can question. Test it in interview: give the candidate last year’s capital movement and ask for the three sentences they would put in front of the board. For wider regional searches, see specialist recruitment across Asia Pacific.
Should the brief require Hong Kong RBC experience?
One line I would strike from any Hong Kong capital brief is a minimum number of years of Hong Kong RBC experience. A search is a problem statement, not a vacancy, and that line fails the first check: how big is the pool? The regime is new, so the pool is tiny and fully employed. The criteria are too narrow. What the insurer actually needs is someone who has run a risk based capital calibration, owned an ORSA, and can explain a capital movement to a board. That person exists in several regimes. Rewrite the brief around the work, and the shortlist looks very different.
Frequently asked questions(FAQs)
1. When did Hong Kong's risk based capital regime start?
Hong Kong’s risk based capital regime for insurers commenced on 1 July 2024. The government announced on 3 May 2024 that 14 pieces of subsidiary legislation had been gazetted to implement it. In 2026 the government gazetted further rules on public disclosure and on valuation and capital, so the regime continues to develop after go live.
2. What are the three pillars of Hong Kong RBC?
The first pillar sets quantitative capital requirements, with the prescribed capital amount calibrated to a 99.5 per cent level over one year. The second covers governance and enterprise risk management, including an ORSA at least annually. The third covers regulatory reporting and public disclosure, which the Insurance (Public Disclosure) Rules gazetted on 22 May 2026 now set out.
3. What did the 2026 Hong Kong insurance rules change?
On 22 May 2026 the government gazetted the Insurance (Public Disclosure) Rules, in force on gazettal for financial years beginning on or after 1 January 2025, and the Insurance (Valuation and Capital) (Amendment) Rules 2026. The amendment takes effect on 31 December 2026 and refines capital for catastrophe and reserve risk, among other changes.
4. Do actuaries need Cantonese to work in Hong Kong?
Usually not for technical capital, valuation or model validation roles, where the work and most governance run in English. Cantonese matters more where a role faces local customers, distribution or claims, and Putonghua can matter with a mainland parent. Employers should state any language requirement in the brief rather than raise it late in the process.
If you are building or strengthening an RBC team and want a specialist view on the brief before you go to market, Start a conversation.
Talk to us about your hiring
Get in touch →More reading
Related intelligence
-
Recruitment
What a new insurer in the UAE or Saudi Arabia should hire first
Hire the people a regulator will judge you on before anyone else: actuarial cover from a licensed actuary,…
Read the article → -
Recruitment
How to set up an actuarial function in a new or growing insurer
Start with what your regulator requires the actuary to be and to sign, then hire around that. For…
Read the article → -
Recruitment
One GCC or several? Designing a specialist function across hubs
One GCC or Several? When to Concentrate a Specialist Function and When to Split It Once a firm…
Read the article →